CORPORATE FINANCIAL SERVICES / 02
Cash Flow & Liquidity Analysis
Understand the gap between expected receipts and payment commitments. Build a near-term cash view, examine timing pressure and identify the assumptions that matter most to the business’s available cash position.
SERVICE SCOPE
What the work covers.
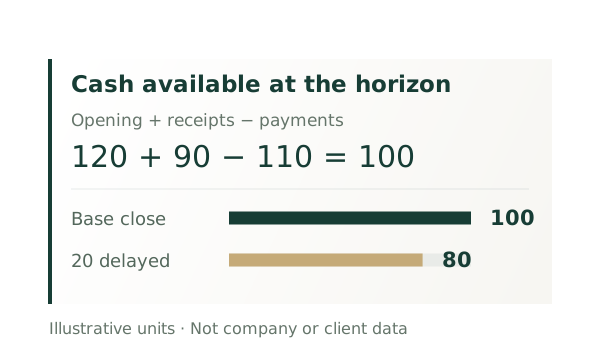
A profitable period can still contain weeks when payments fall due before receipts arrive. We organise opening cash, expected collections, supplier payments and operating commitments into a time-based view, often covering thirteen weeks. The review examines concentrated payment dates, uncertain receipts and the effect of timing changes. The result is a clearer picture of potential cash pressure and the items management should monitor more closely.
Who this is for
- Businesses with uneven receipts or concentrated payment dates.
- Companies whose cash position is difficult to read from profit reports.
- Management teams planning near-term operating commitments.
BUSINESS QUESTIONS
What management needs to examine.
Which weeks may put the greatest pressure on available cash?
How would delayed receipts change the near-term position?
Which payment and collection assumptions need the closest attention?
ANALYTICAL METHODS
How we examine the information.
Receipts and payments scheduling
Place expected cash movements into weekly periods using available collection dates and payment commitments.
Timing sensitivity review
Examine how selected delays in receipts or changes in payment timing affect the projected cash position.
Liquidity pressure identification
Locate periods with limited headroom and trace the receipts, commitments and assumptions responsible.
DELIVERABLES
What your business receives.
Near-term cash schedule
A weekly view of opening cash, expected movements and projected closing balances over the agreed period.
Cash timing assessment
An explanation of pressure periods and the effect of selected changes in receipt or payment timing.
Liquidity watchlist
The significant dates, uncertain receipts and assumptions management should revisit as new information becomes available.
The proposal specifies the reporting format, analysis period and level of detail. No particular commercial or financial outcome is guaranteed.
WORKING PROCESS
How the assignment is arranged.
- 01
Choose the cash review period
Agree the opening position, time intervals and operating commitments to include.
- 02
Schedule expected movements
Organise available receipts and payment information by expected cash date.
- 03
Examine timing pressure
Review projected balances and the effect of selected delays or concentrated payments.
- 04
Set the monitoring priorities
Explain pressure periods and identify the assumptions management should update first.
CONTACT CLEARPATH
Discuss cash flow & liquidity analysis.
Tell us about the financial question, the period under review and the support your business needs.